Laurence S. Bolchoz Jr. spent 14 years building a bank based in Myrtle Beach. On Oct. 1, the company that owns it started listing its headquarters in his hometown.
Coastal Carolina Bancshares, the parent of Coastal Carolina National Bank, completed its merger with Beacon Holding Company, the parent of Mount Pleasant’s Beacon Community Bank, that day. Its announcement describes the holding company as “now headquartered in Charleston, South Carolina.” The Post and Courier reported that the holding company is moving its headquarters from Horry County to the Charleston region, while the bank itself remains based in Myrtle Beach.
Bolchoz, a Charleston native, keeps the titles of president and CEO, the newspaper reported.
“The successful completion of our merger of equals with Beacon Community Bank marks an exciting new chapter for our organization,” he said in the announcement. “By bringing together two community-focused institutions with shared values, strong cultures, and a commitment to exceptional customer service, we have created an even stronger banking franchise positioned for long-term growth.”
From one branch to a statewide map
Coastal Carolina National opened for business in June 2009, and Bolchoz joined as president and CEO of the bank and its holding company in March 2012, according to the bank’s history. It opened its first branch, in Garden City, in January 2013.
Since then the bank has spread across the state and beyond it. It bought Aiken-based VistaBank in 2016, according to the bank, and its parent began trading on the over-the-counter market in 2017 after a $16.5 million private placement. Outside the Charleston area, its branches run from Garden City, North Myrtle Beach and Conway to Aiken, Columbia, Orangeburg, Greenville and Spartanburg, according to the company. In November 2024 it opened its first North Carolina office, in Ocean Isle Beach, and in April it broke ground on a permanent branch there.
Before the merger, Coastal reported $1.351 billion in total assets at June 30, up 14% from a year earlier. Its net income for the first half of 2026 was $6.2 million, compared with $4.9 million a year earlier.
The Beacon deal
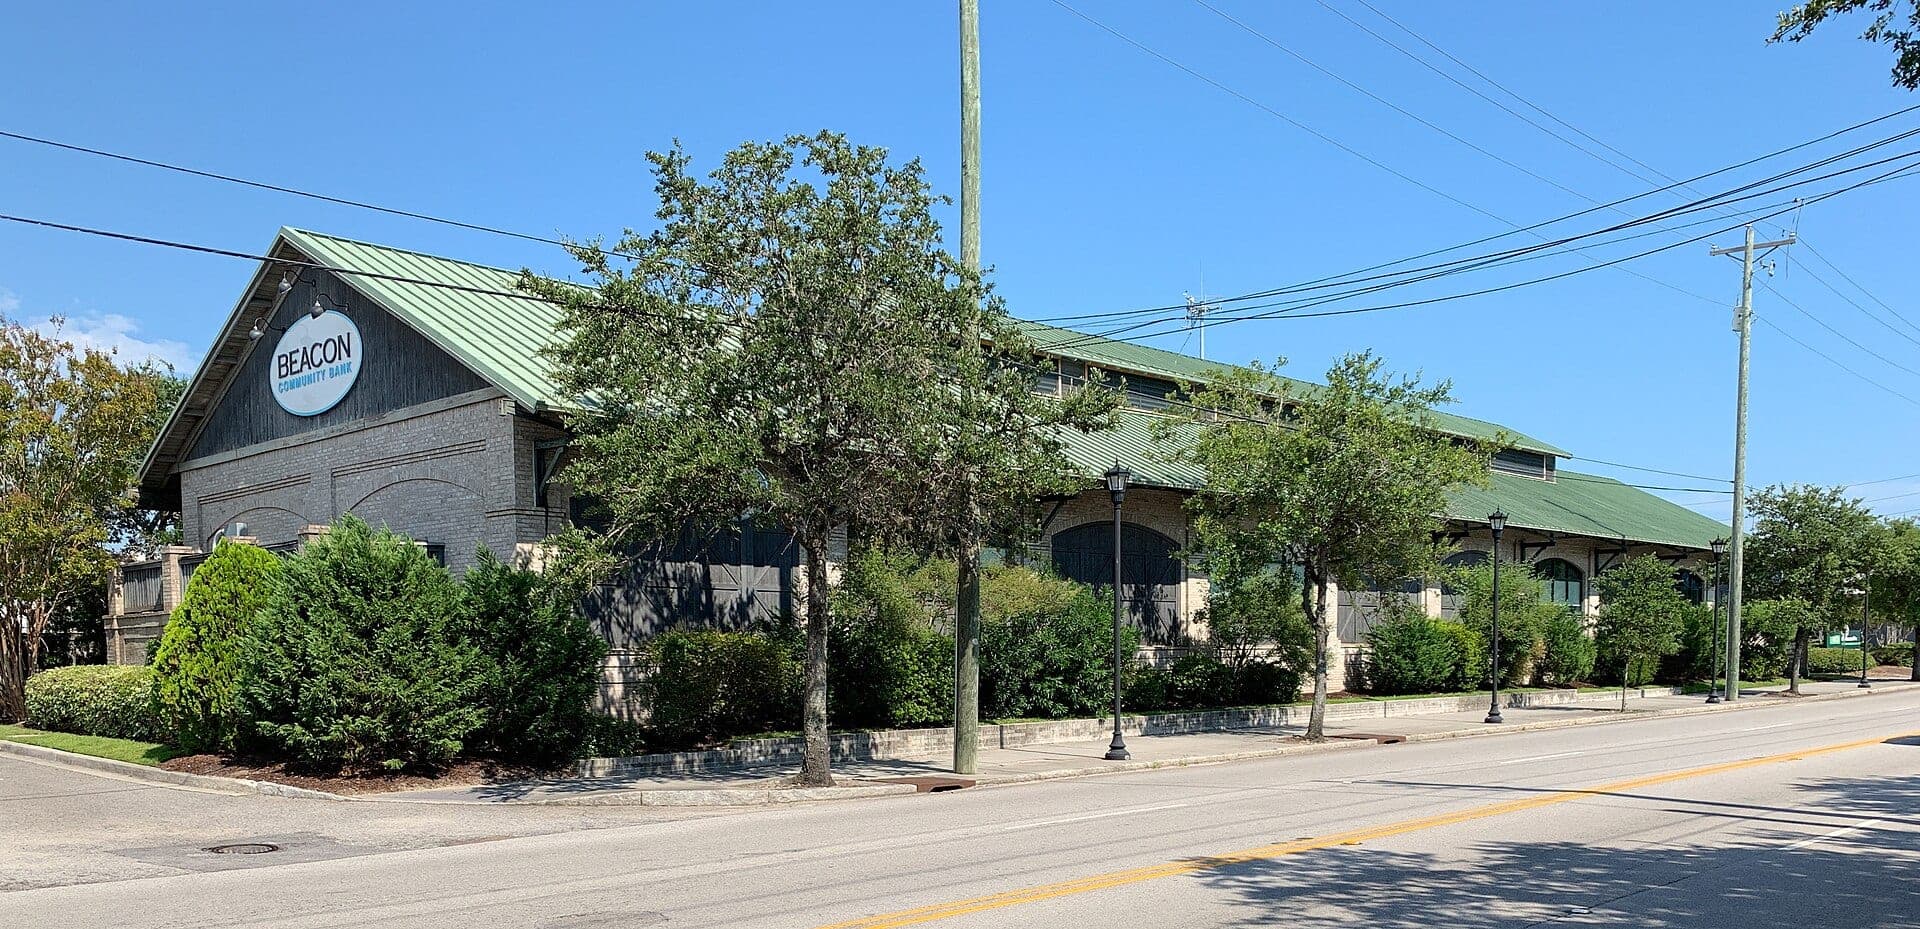
The two companies announced the deal May 29. Beacon opened on East Bay Street in downtown Charleston on Jan. 8, 2018, The Post and Courier reported, after local organizers raised about $37 million from more than 300 investors. It was the first true startup bank approved in South Carolina in nearly a decade and grew to six offices in the Charleston market, with a headquarters in Mount Pleasant’s Six Mile community, the newspaper reported.
The all-stock deal, described as a merger of equals, gave Coastal’s shareholders 56% of the combined company, The Post and Courier reported. Beacon co-founder and Lowcountry car dealer Tommy Baker became chairman of an expanded 15-member board. Beacon’s chief executive since its founding, Brooks Melton, became executive vice president and chief risk officer.
The combined company has about $2.3 billion in total assets, $2.0 billion in deposits and $1.8 billion in loans, with 16 branches and a loan production office from Charleston to Wilmington, N.C., and inland to the Upstate, according to the announcement.
“We believe the strong cultural and operational alignment of our organizations will drive profitability and enhance shareholder value, and benefit our customers, employees and the communities we serve,” Bolchoz said when the deal was announced in May, The Post and Courier reported.
What changes, and when
For now, Beacon’s offices operate as “Beacon Community Bank, a division of Coastal Carolina National Bank,” according to the company. Beacon’s systems are scheduled to be converted to Coastal’s in mid-March 2027, when the combined bank will be renamed Beacon Bank, N.A.
The bank told customers that accounts, account numbers, debit cards and online banking will not change in 2026 and that it will give at least 30 days’ notice before any changes. Shares of the holding company continue to trade under the ticker symbol CCNB.